Turning 35 is more than just another birthday for many Singaporeans, it is a milestone that opens the door to one of the most overlooked wealth building opportunities in Singapore; buying your first resale HDB flat.
Unfortunately, many singles continue to delay homeownership because they believe they cannot afford it. They assume buying property requires hundreds of thousands of dollars in cash, an overwhelming mortgage, and years of financial stress.
The reality is often very different.
If you are 35 years old or above, have never owned a property before, and are eligible to purchase a resale HDB, you may have access to grants, CPF financing, and an opportunity to generate rental income from spare bedrooms. When planned carefully, your monthly cost of owning a home may be much lower than you expect.
More importantly, every mortgage payment helps build ownership in an asset that belongs to you. Continue reading to find out why buying a resale HDB at 35 could be one of the best financial decisions you make. I will also run with you on the calculations on affordability and costs to buy one.
Why Age 35 Is a Game Changer for Singles
One of the biggest advantages of turning 35 is becoming eligible to buy a resale HDB flat as a single under the Single Singapore Citizen Scheme. For years, many singles assume property ownership is something that only married couples can enjoy. As a result, they continue living with their parents or rent a room while postponing the decision to buy. However, once you reach 35, your financial options expand significantly.
Instead of waiting indefinitely, you now have the opportunity to purchase your own home, build equity, and begin your journey towards long-term financial security. If you are 35 years old now and have not done a financial analysis on whether you can afford a resale HDB then you should contact me today.
The Biggest Myth About Buying Property in Singapore
Whenever people hear the word "property," they immediately think about expensive condominiums, million-dollar homes, and enormous mortgages. This mindset discourages many first-time buyers before they even explore their options. Not everyone needs to buy a condo to have a place that is comfortable to stay.
The truth is that buying a resale HDB can be significantly more affordable than most people realise. The fact is that many resale HDB nowadays are getting older and the prices is much cheaper than newly MOP Resale Flats. You just need to know where to choose. First time in Singapore can finance their property with a range of methods such as the ones below, which helps to reduce cash outlay.
- CPF Ordinary Account savings
- Government housing grants (subject to eligibility)
- HDB or bank financing (depending on eligibility and preference)
- Monthly CPF contributions to help service the mortgage
When these are taken into consideration, the amount of cash required may be far lower than expected. Rather than focusing only on the purchase price, successful buyers look at the total cost of ownership after grants, CPF usage, financing, and ongoing affordability.
First-Time HDB Grants Can Make a Huge Difference
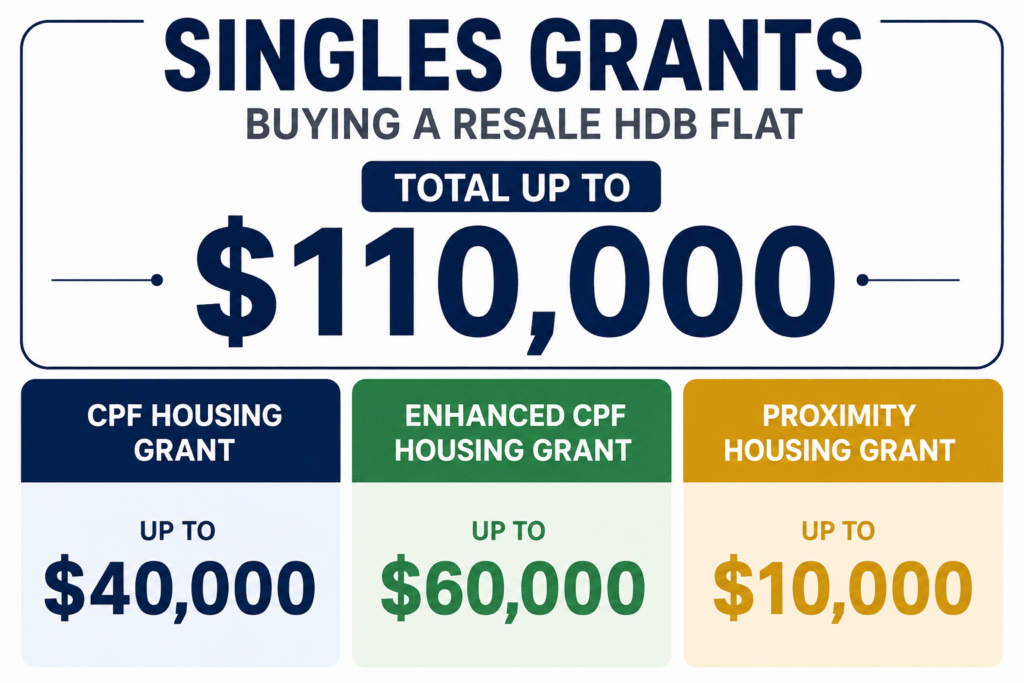
One of the biggest advantages for a first-time HDB buyer is the availability of Singles housing grants, subject to prevailing eligibility criteria. These grants can substantially reduce the effective purchase price of your resale HDB. Many buyers are surprised to learn that they do not necessarily need to finance the full purchase price themselves. Depending on your circumstances, grants may significantly lower the amount you need to borrow, reducing your monthly mortgage and making homeownership much more achievable. Before purchasing, always check the latest HDB grant eligibility, income ceilings, and financing rules, as policies may change over time.
A Home for Investment and Own Stay
Most people think a home is simply a place to stay. Successful property owners think differently. The goal is to own assets that can generate you cash flow and wealth. It is hard for you to understand the power of owning an asset until it generates passive income for you.
A property can be:
- Your home.
- Your largest financial asset.
- A hedge against rising housing costs.
- A source of rental income.
- A long-term wealth-building vehicle.
When you own your own home, every mortgage payment increases your equity in the property. Unlike paying rent which provides no ownership, mortgage repayments gradually increase the equity in the property that belongs to you. Over the years, this can become a significant component of your net worth. Imagine paying your flat fully and renting out both rooms you can easily cover your daily expenses and this will definitely reduce stress that formed from trying to cover daily expenses.
If you think about it, your asset value remains or increases while you get additional passive income every month and your equity continues to increase every month. This is the power of real estate investment that you should take advantage of as soon as possible. I will work out the numbers with you later and you can see if it is a good deal for you.
Can Rental Income Help Offset Your Mortgage?
One of the most compelling reasons why a resale HDB for singles makes financial sense is the potential to rent out spare bedrooms. Think about your own lifestyle. As a single, do you really need three bedrooms? Probably not.
Many singles comfortably occupy one bedroom while having one or more spare rooms available. Instead of leaving these rooms empty, you may choose to rent them out to generate rental income. This changes the economics of homeownership.
Rather than relying entirely on your salary to pay the mortgage, rental income may help offset a significant portion of your monthly repayments. In some situations, depending on rental demand, financing structure, and loan size, rental income may even exceed the monthly mortgage. While this is never guaranteed, it illustrates how a home can become an income-producing asset rather than simply an ongoing expense.
You're Not Just Paying a Mortgage, You're Building Equity
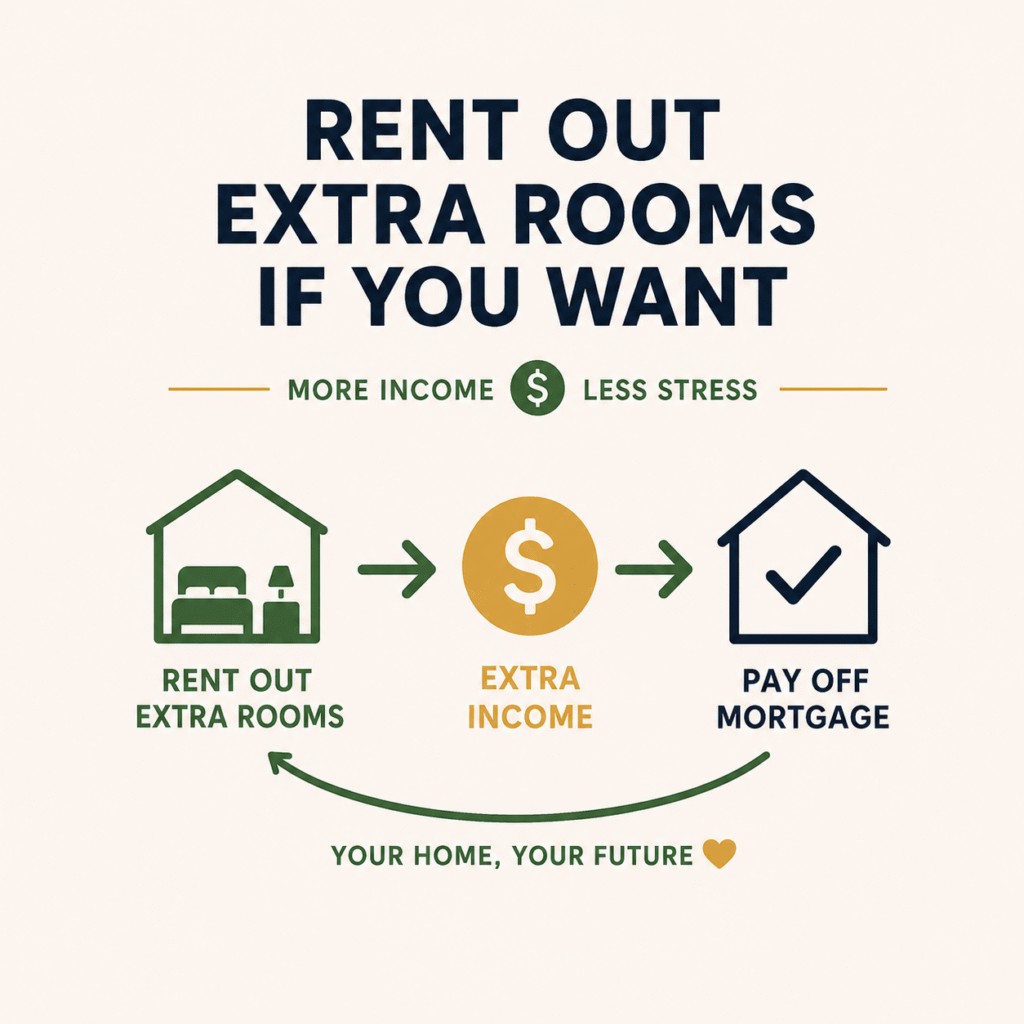
Many people see a mortgage as a burden but do you know that every month when you pay for your mortgage, it reduces the amount of loan and it increases your equity in the property. And if you are renting out the rooms, you will be able to use the rental income to offset the mortgage and it would mean that you are using other peoples money to pay for your asset.
Over the years, you have unknowingly force yourself to accumulate value in the property which you can continue to stay on or consider restructuring of property portfolio after your MOP period. With the amount of value in the property, you will have more options out there in future. This is one reason why property ownership has long been regarded as a cornerstone of wealth accumulation.
In-depth Calculation Buying a $500,000 4 Room Resale HDB
This is just an example of a 4-room resale HDB that cost $500,000. You might be skeptical, but there are really such prices in the market right now. Our focus here is on the calculation for the cost that you need to pay upfront all the way till selling the flat five years later. How much equity do you have? How much do you make from the Property?
As a single buyer, unless you have a higher income, you will likely have a lower loan eligibility than a dual income household. Even your grants will be halved. But up till an age of 35, you would likely have worked for at least 8 to 10 years. Which you would have slowly accumulated funds in your CPF account which can be utilised. So let's now go into the calculation of how much does it cost to buy a $500,000 4 room resale HDB.
Below I have list down separately based on the additional costs involved and financing avenues, do note that cost varies depending on many factors such as provider chosen, this is only based on my best estimate.
Financing Avenues
- First-time buyer CPF grants.
- Use CPF savings for part of the purchase.
- Finance the remaining balance through an HDB or bank loan.
- Rent out eligible spare bedrooms to generate rental income.
Additional Costs and On-going Costs Involved
- Buyer Stamp Duty
- Legal Fees
- Fire Insurance
- Service & Conservancy
- Utility Bills
- Wifi Bills
- Property Tax
- Renovation costs
- Furniture costs
- Mortgage Interest
Funds Required to Buy House
For the whole purchase if you have enough CPF, the minimum cash needed is 5% which is $25,000. Renovation and furniture cost includes appliances like oven, washing machine, sofa. We will assume that you are purchasing a house that requires minimal renovation. Look carefully, you are only buying a house that is worth $500k for only $126K, this is the power of leveraging when buying real estate.
| Total Expenses & Downpayment | ||
|---|---|---|
| Buyer Stamp Duty | $9,600.00 | |
| Legal Fees | $1,800.00 | |
| Valuation Fees | $120.00 | |
| Resale Application Fees | $80.00 | |
| Downpayment 25% | $125,000.00 | Minimum 5% cash |
| Renovation & Furniture Costs | $40,000.00 | |
| CPF Housing Grant | - $40,000.00 | Singles |
| Proximity Housing Grant | - $10,000.00 | |
| Total Purchase Outlay | $126,600.00 | CPF or Cash |
Ongoing Monthly Costs
All the ongoing cost after collecting rental results in a positive cashflow monthly, or rather you stay in the house for free. This is all on the surface, looking deeper, the monthly mortgage your tenant paid is actually putting more equity into the property for you after deducting the interest. Also you have not used your CPF for the payment of mortgage. There are some owners who use CPF to pay for the monthly mortgage so that they receive more cash after receiving rental income, somehow indirectly taking out money from the CPF. However, it is not recommended unless you can find another investment vehicle that can give you a better return than CPF. Also you must make sure you invest the money and not use it!!
| Ongoing Costs (Monthly) | ||
|---|---|---|
| Fire Insurance | -$55 | |
| Service & Conservancy | -$80 | |
| Utility Bills | -$170 | |
| Wifi Bills | -$40 | |
| Property Tax | -$2 | |
| Monthly Mortgage | -$1,600 | 2% Interest, 25 years, 75% Loan |
| Rental Income | $2,000 | 2 rooms x $1000 |
| Total Monthly Cost | $53 | POSITIVE Cashflow (Without Using CPF) |
Estimated Returns After Selling 10 years
I did an analysis based on a 10 year holding period, with property price appreciating at a modest 2% y-o-y. After 10 years, the remaining loan balance would be around $247K. Over the years the tenants have been paying the mortgage for you and what sales proceeds you will get after deducting loan balance and costs is around $340k. I did not separate the CPF and cash, as CPF will be usable for your next purchase even though it is returned back into your CPF OA.
The annualised returns, while staying for "free" monthly is around 10%!
| Discounted Cashflow Investment Returns | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| Cashflow | Year 0 | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 | Year 6 | Year 7 | Year 8 | Year 9 | Year 10 |
| Buyer Stamp Duty | -9,600 | ||||||||||
| Legal Fees | -1,800 | ||||||||||
| Valuation Fees | -120 | ||||||||||
| Resale Application Fees | -80 | ||||||||||
| Downpayment 25% | -125,000 | ||||||||||
| Renovation & Furniture Costs | -40,000 | ||||||||||
| CPF Grants | 50,000 | ||||||||||
| Fire Insurance | -55 | -55 | -55 | -55 | -55 | -55 | -55 | -55 | -55 | -55 | |
| Service & Conservancy | -80 | -80 | -80 | -80 | -80 | -80 | -80 | -80 | -80 | -80 | |
| Utility Bills | -170 | -170 | -170 | -170 | -170 | -170 | -170 | -170 | -170 | -170 | |
| Wifi Bills | -40 | -40 | -40 | -40 | -40 | -40 | -40 | -40 | -40 | -40 | |
| Property Tax | -2 | -2 | -2 | -2 | -2 | -2 | -2 | -2 | -2 | -2 | |
| Monthly Mortgage | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | -1,600 | |
| Rental Income | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | |
| Selling Price (2% yoy increase) | 600,000 | ||||||||||
| Remaining Loan | -246,999 | ||||||||||
| Cost to sell (hdb, agent, legal fee). Approx | -13,660 | ||||||||||
| Total Cashflow | -126,600 | 53 | 53 | 53 | 53 | 53 | 53 | 53 | 53 | 53 | 339,394 |
| Annualised Return | 10.39% | ||||||||||
Want To Estimate Your Returns?
Calculate your returns with all the detailed costs involved. No hiding your true returns. Numbers don't lie. What if your property price remains the same? Different property requires different analysis, whether you're conservative about the unit or bullish, I can factor into the calculations. Start your property journey right!
Finally, A Space You Can Truly Call Your Own
While the financial benefits of homeownership are significant, owning your own home is about much more than building wealth. It represents independence, freedom, and having a space that truly belongs to you. Instead of living around someone else's routines or rules, you have the privacy to enjoy your own lifestyle, the flexibility to work from home comfortably, and the freedom to decorate and personalise your home to reflect your personality.
For many singles, these lifestyle benefits are just as meaningful as the financial rewards. Having your own home means you can host family and friends whenever you like, enjoy the peace and comfort of your own private space, and make decisions about your home without compromise. Beyond providing a roof over your head, homeownership offers a greater sense of stability, accomplishment, and confidence, knowing that you are building a future in a place you can truly call your own.
The Cost of Waiting to Buy Your First Home
Many people put off buying their first home because they believe there will always be a better time in the future. Whether it's waiting for a higher salary, lower property prices, or simply feeling more financially prepared, the decision often gets pushed back year after year. However, every year you delay buying is another year you are not building equity in a property that you own. If you are eligible to rent out spare bedrooms, it could also mean missing out on potential rental income that may help offset your housing costs, while your long-term financial goals remain on hold.
Although no one can predict how property prices will perform in the future, one advantage you can control is time. The earlier you begin your homeownership journey, the more time you have to pay down your mortgage, build equity, and potentially benefit from any long term appreciation in your property's value. Rather than waiting for the "perfect" moment which may never come, it is often more beneficial to understand your affordability today and make an informed decision that aligns with your financial goals.
Is a Resale HDB a Good Singapore Property Investment?
Honestly, resale HDB does not appreciate as much as a BTO in normal scenarios. However, as a single, you are limited to only 2 room flexi for BTOs. While you are not restricted to buying any type of resale HDB as a single Singaporean. Therefore, I believe a wise choice is choosing for a resale of a bigger space as you might have a family in future and a bigger space is definitely better if you can afford it.
Looking at a cashflow perspective, generally resale HDB is located closer to the MRT stations, which helps to command higher rents. And you need rooms to rent out, if you're getting a 2 room flat, there is no way for you to rent part of it out.
Let's not forget about your goal, to get you your first property that you can stay in and invest in. We are not just getting any property, proper checks have to be done, making sure you're buying a resale HDB of value.
Like any investment, there are risks. Property prices can fluctuate, rental demand can change, and financing costs may vary. The key is to purchase a property that fits your budget and long-term objectives rather than stretching beyond your means.
Conclusion
If you're 35 or older and have never owned a property, don't let outdated assumptions stop you from exploring your options. Have an open mind, spend some time and look through the above information and calculation. If you need someone to explain in detail and to assist you for the whole process, just give me a call.
A resale HDB could be far more affordable than you realise, especially if you qualify for first-timer HDB grants and make full use of your CPF savings. Renting out spare bedrooms may help offset part of your monthly mortgage while you continue building equity in your home.
Owning a property is not just about having a roof over your head. It's about creating long-term financial security, enjoying your own space, and making your money work harder for you. The best time to start understanding your options is now. Review your finances, calculate your affordability, and let me help you with your first property purchase with facts and figures.
The earlier you begin your homeownership journey, the sooner you can start building an asset that has the potential to support both your lifestyle and your future.
Start Your Property Journey Right!
Have an open mind, learn about real estate investing. I am a person that focus on facts and figures, don't just buy emotionally, you will likely make a mistake. You can not predict the future but you can act on your best knowledge of the present!